On this page
UK credit card debt · drainage model
£97.2bnby2049
UK credit card debt
£97.2bnby2049
UK credit card debt
SRC · UK Finance / BOE Illustrative projection
Updraft’s 2026 forecast puts total UK credit card interest payments at around £17,151,000,000. That is interest paid on consumer credit in a single year.
Where borrowers are only meeting minimum payments on credit card repayments, a large share of each monthly payment goes on interest rather than reducing the balance. Over time, this can extend how long it takes to clear the debt and increase the total cost of borrowing.
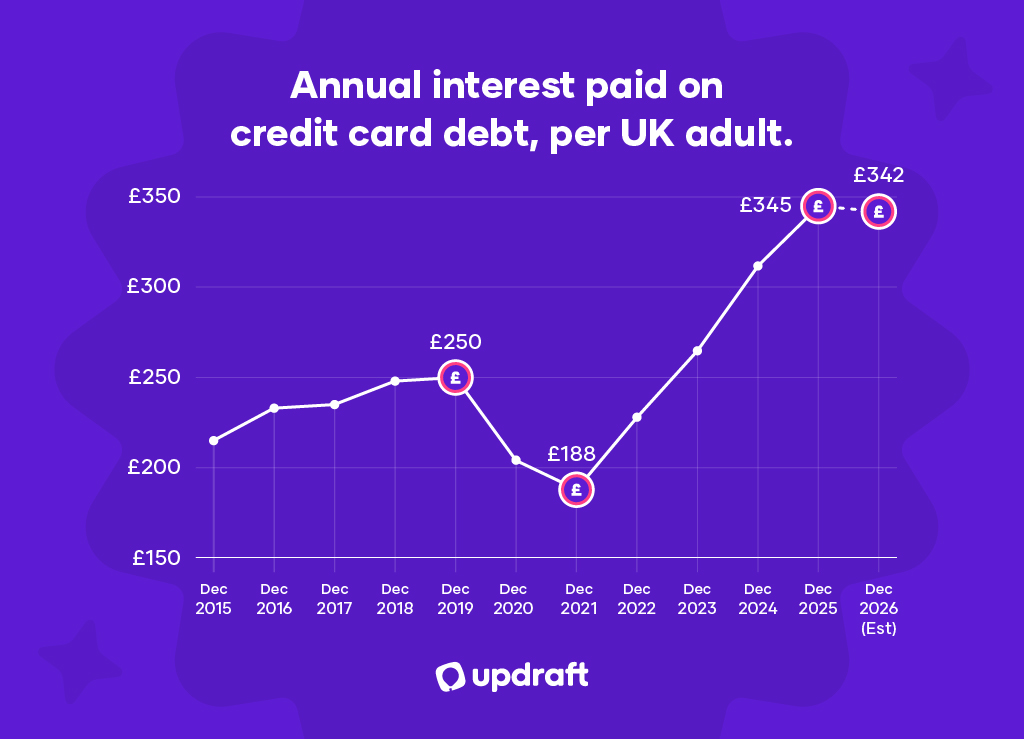
The average Brit is estimated to have £1,400 of credit card debt in 2026. Taking into account the average credit card interest rate of 21.71% (Bank of England, September 2026; 21.56% as at December 2025), this means that the average credit card interest paid per person in 2026 is forecast to total £304.
For borrowers making only the minimum payment, most of each monthly payment goes to interest rather than reducing the balance. On a £1,400 balance at 21.71% with a typical minimum payment formula, it can take over a decade to clear the debt, and the borrower can pay back close to as much again in interest as they originally borrowed.
Since 2016, average credit card debt per adult has grown by around 13%, from £1,241 to £1,400 in 2026 (source: Bank of England, ONS).
Over the same period, the average credit card interest rate has risen from 18.38% in 2016 to 21.71% in September 2026 (source: Bank of England). Average interest paid per adult on credit card debt has risen from £228 in 2016 to £304 in 2026, an increase of around 33%.
As a large share of the minimum payment on high-rate debt goes to interest, clearing the balance with minimum payments only can take many years. The combination of higher rates and bigger balances means that more of every monthly payment is now servicing interest than it was ten years ago. The drain has grown.
In Updraft’s forecast, total UK credit card debt will reach £79,000,000,000 by the end of 2026, equivalent to average credit card interest payments of around £304 per adult over the year.
Updraft analysis also suggests that a significant proportion of UK credit card debt is not currently consolidated. UK Finance figures show that around 47.5% of credit card balances were incurring interest in May 2025.
| Total Credit Card Debt | UK Adult Population | Avg Card Debt per Adult | Avg Card Interest per Adult | Total Annual Card Interest |
|---|---|---|---|---|
| £79bn | 56.42m | £1,400 | £304 | £17.2bn |
Source: Updraft forecast, December 2026 estimated, based on Bank of England and ONS data. Methodology below.
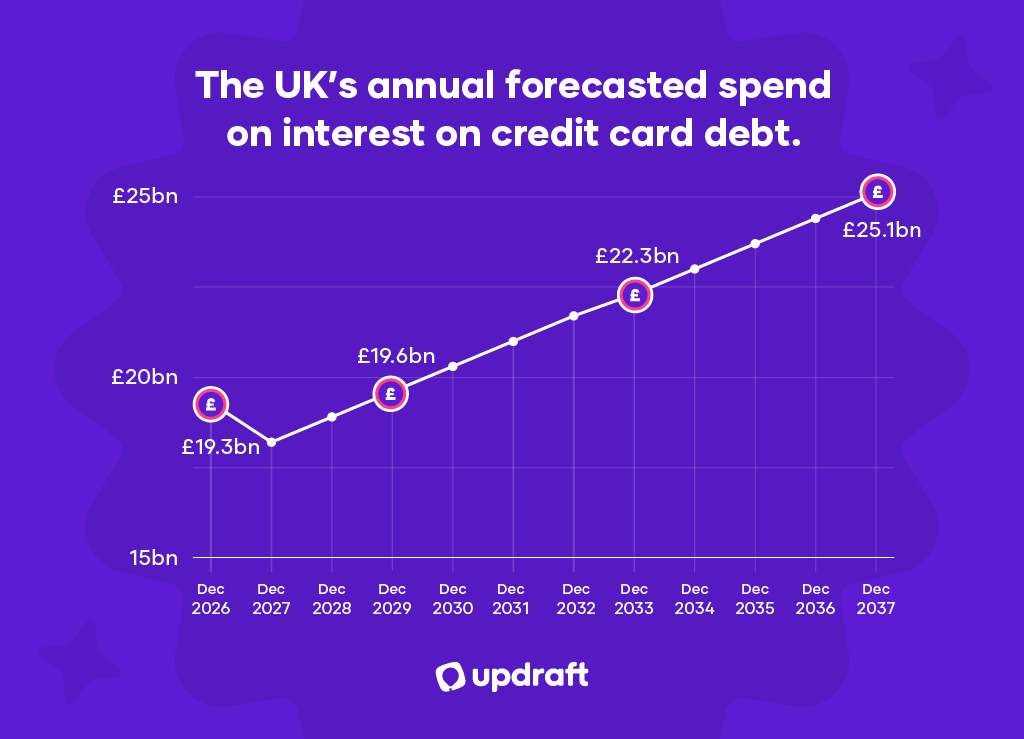
Looking further ahead, if UK debt and interest costs continue to grow at the pace seen over the last five years, Updraft’s analysis suggests that total UK credit card interest payments could reach £25 billion by 2037.
Projections based on 5-year compound growth rates (2021 to 2026). These are illustrative projections based on historic growth rates only. They do not account for policy changes, interest rate movements or shifts in borrowing behaviour.
| Milestone | Year | From (Dec 2026 Prediction) | Growth Rate |
|---|---|---|---|
| Total credit card interest hits £25bn | 2037 | £17.2bn | 11.28% p.a. |
| Credit card debt per adult hits £1,503 | 2054 | £1,400 | 10.22% p.a. |
| Total UK credit card debt hits £100 billion | 2053 | £79bn | 6.12% p.a. |
Projections: Updraft analysis, based on 5-year compound growth rates in underlying Bank of England and ONS data (2021 to 2026). Linear trend only, not modelled for policy or behavioural change. Full methodology is available below.
If credit card rates and balances hold at current levels, the drain on UK consumers from card interest grows alongside the underlying debt. Closing the rate gap by refinancing onto lower-cost products is one route to slowing it. For those who cannot, paying more than the minimum each month is the most direct way to keep more of each payment working on the balance rather than the interest.
Updraft analysis suggests a significant share of UK credit card debt is not currently consolidated. The table below shows how total credit card debt has grown over the last decade, using Bank of England data, alongside Updraft’s estimate of the unconsolidated share.
| Month/Year | Total UK Credit Card Debt | % not consolidated |
|---|---|---|
| December 2015 | £62.8bn | 79% |
| December 2020 | £60.7bn | 84% |
| December 2025 | £78.3bn | 83% |
| December 2026 (forecast) | £79.0bn | 82% |
So what are the options? There are a few routes, and the right one depends on your circumstances:
If you are worried about your debts, speak to one of the free advice services above before committing to a new product.
The figures in this piece come from the following sources:
Forecasts for 2026 and the 2037, 2053 and 2054 milestones use the 5-year compound annual growth rate in each underlying series (2021 to 2026), projected forward. This is a linear trend projection only. It does not model policy changes, macroeconomic shocks or shifts in borrowing behaviour, and the milestones should be read as illustrative.
Predicted annual credit card interest cost calculated by multiplying the average credit card debt per adult by the average credit card interest rate.
The figures we quote for the proportion of UK revolving credit that is not consolidated are Updraft’s own estimate, built from Bank of England consumer credit data and our internal analysis of product mix. Full methodology is held on file.
Looking to pay off credit card debt? If you’re looking to consolidate credit card debt and cut down on high interest, check your eligibility for Updraft, or download our app today.
Loans from 15.3% APR (25.9% APR Representative)
25.9% APR Representative based on a £10,000 loan over 60 months at 20.40% fixed interest p.a. Monthly repayment: £283.20. Total repayable: £16,992 (inc. £600 fee). Subject to status and affordability. Consolidating debt may increase the term and total amount repaid. All figures are representative and based upon an assessment of credit and affordability. Terms and conditions apply.
From 15.3% to 41.2% APR, £1,000–£25,000, over 2–5 years available.
How much credit card debt does the UK have?
Updraft forecasts that total UK credit card debt will reach £79 billion by the end of 2026, around £1,400 per adult.
How much credit card interest does the UK pay each year?
About £17.2 billion in 2026 on Updraft's forecast, or around £304 per adult. In 2016 it was £228 per adult.
What is the average credit card interest rate in the UK?
21.71% in September 2026, according to the Bank of England, up from 18.38% in 2016.
How long does it take to clear a credit card with minimum payments?
On a £1,400 balance at 21.71% with a typical minimum payment, it can take over a decade, and you can end up paying back close to as much again in interest.

Facebook-f Instagram Tiktok Linkedin

Updraft is authorised and regulated by the Financial Conduct Authority under firm reference number 810923.
Fairscore Ltd (trading as “Updraft”) is registered in England. Our registered company number is 10868865 and our registered office is at 20-22 Wenlock Road, London, N1 7GU. Updraft is acting as an agent of TrueLayer, who is providing the regulated Account Information Service and is authorised and regulated by the Financial Conduct Authority under the Payment Services Regulations 2017 and Electronic Money Regulations 2011 (firm reference number 901096).
© 2026 Fairscore Ltd

Hi there
Join the waitlist!
Members of our waitlist will receive VIP treatment and early access to our amazing service!
Thanks for joining!
Take action and share with your friends to move up in line!
First Name
Tell your friends
+ 1 each
Custom widget
0
points
23
position
22
in line
